Whitepaper
1 min Read
29 Jun, 2026
Share On


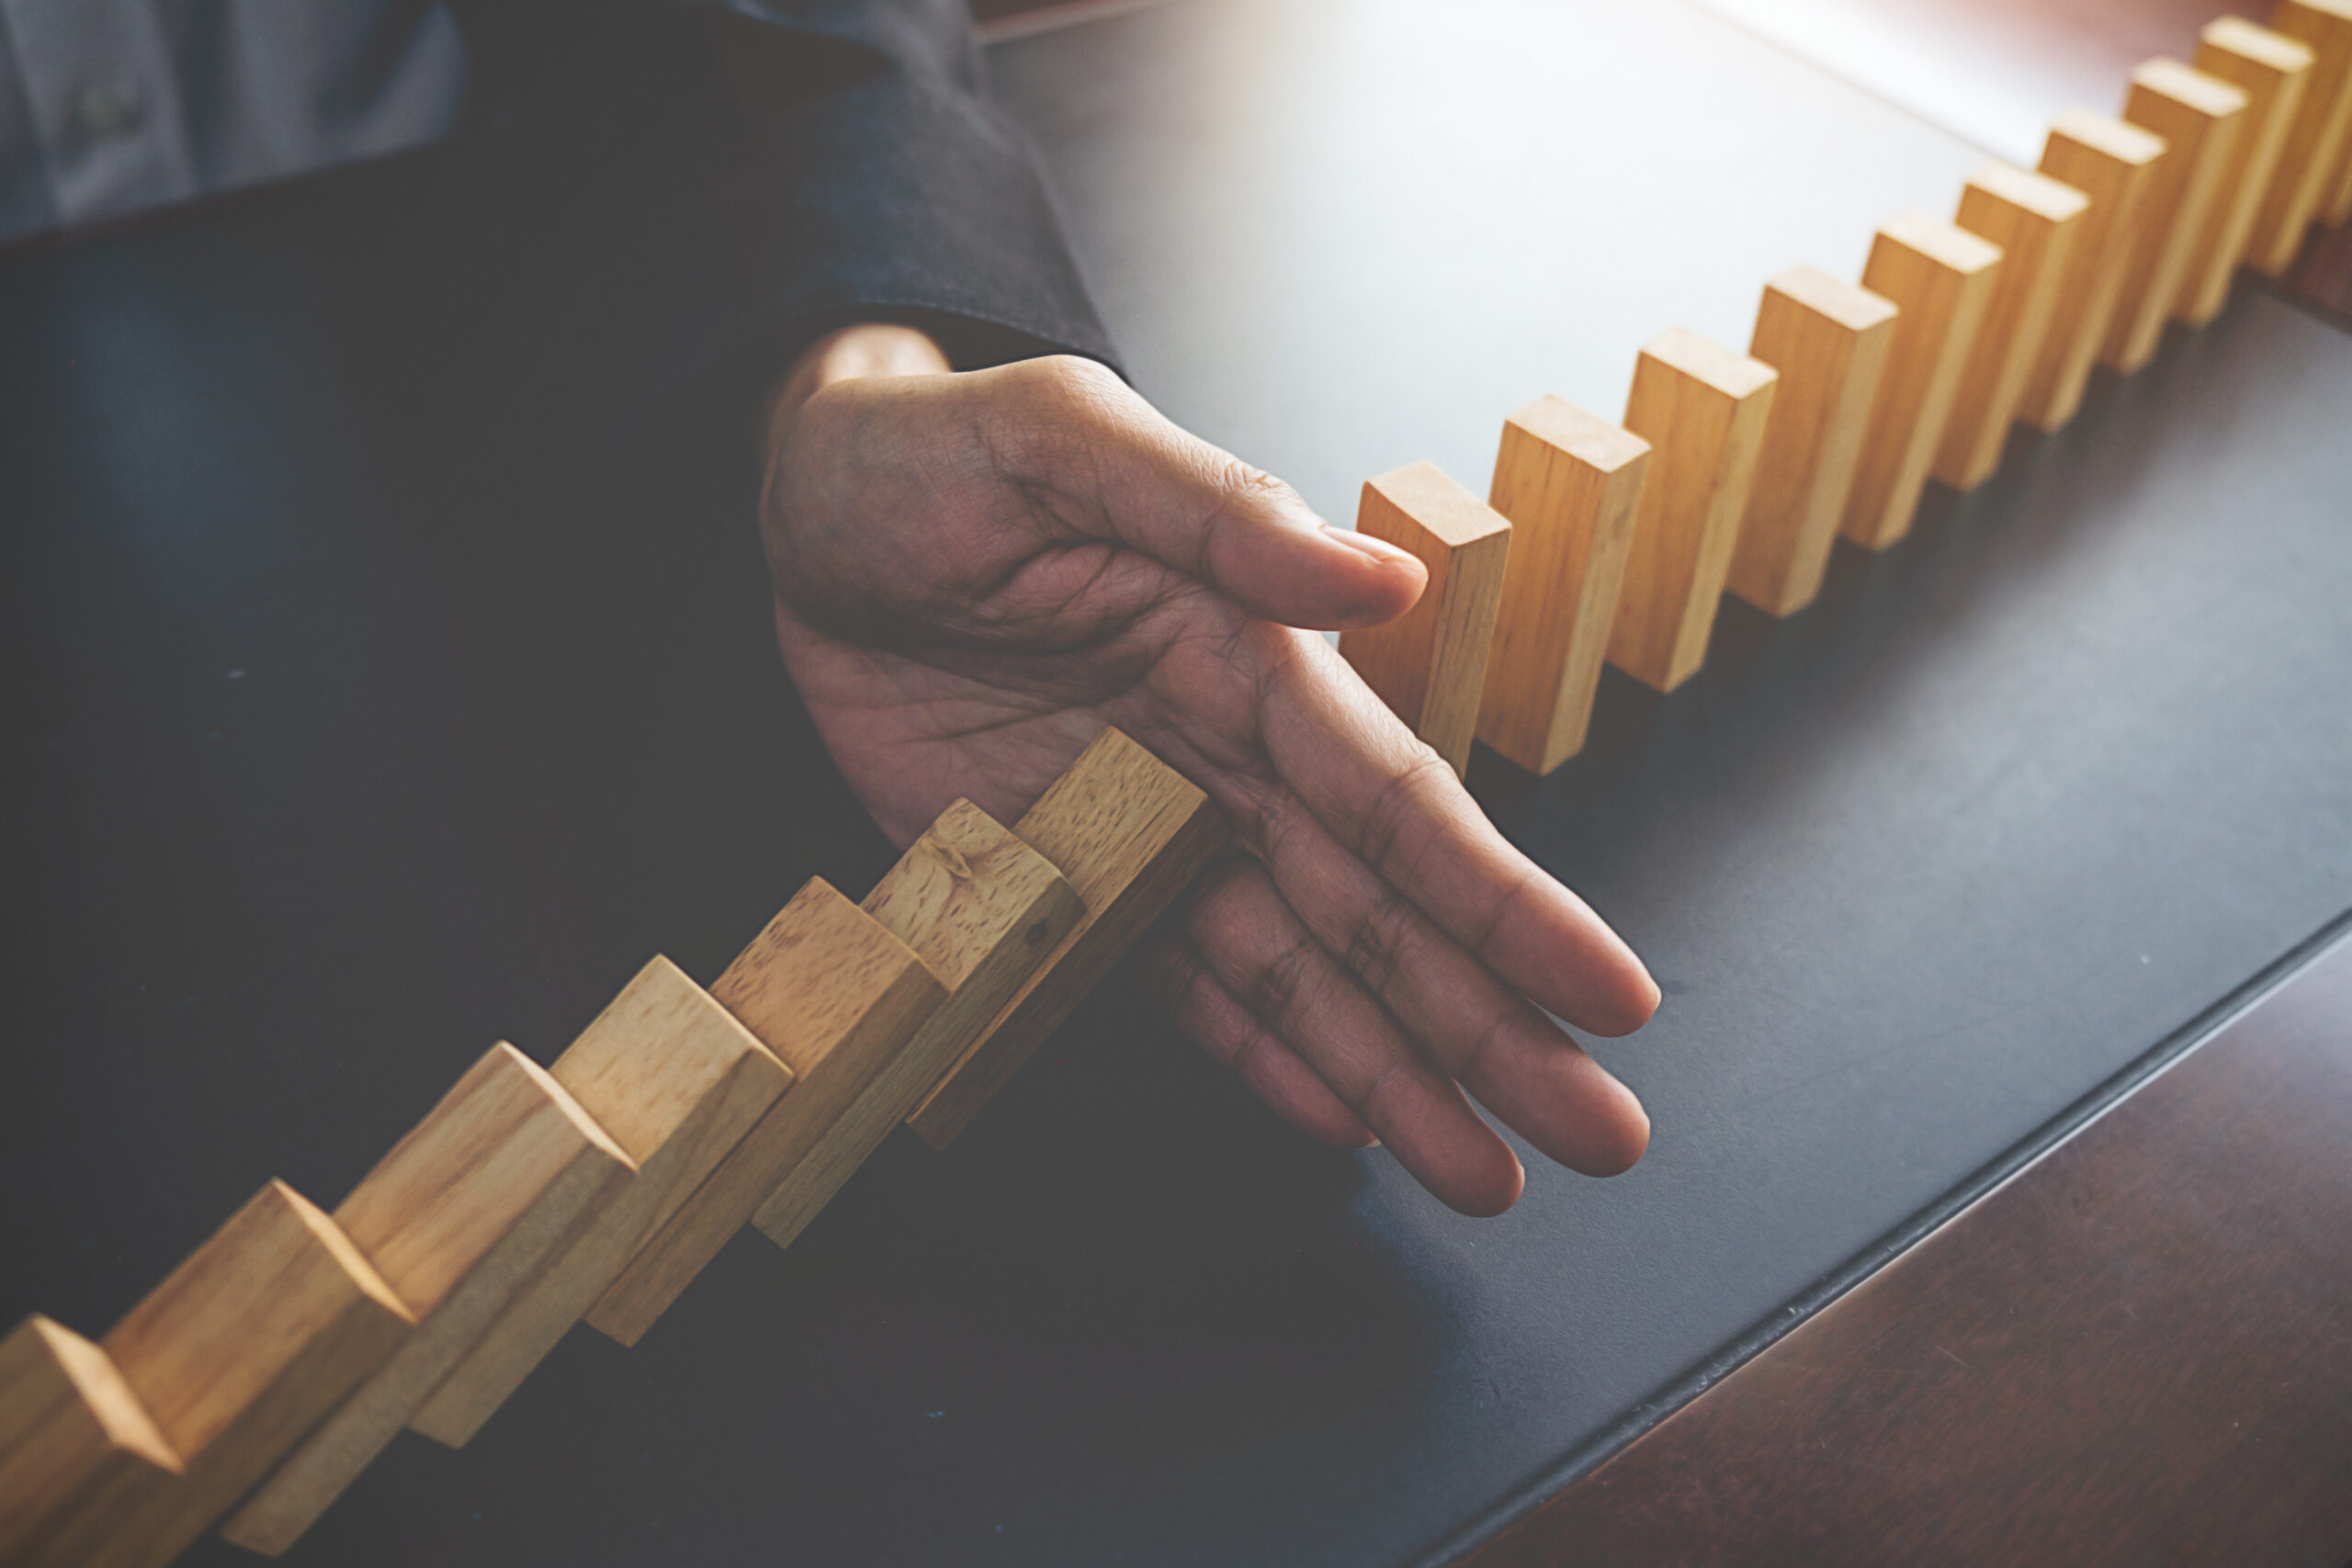
Private credit’s first major liquidity test has exposed structural weaknesses that years of uninterrupted capital inflows concealed. Redemption pressure is reshaping fund liquidity, corporate refinancing, banking linkages, and regulatory oversight. As investment, borrowing, and counterparty risks increasingly converge, C-suite leaders must reassess liquidity assumptions and adopt integrated risk management before tighter credit conditions become more widespread.
Years of uninterrupted capital inflows enabled rapid private credit expansion while masking a structural liquidity mismatch that became evident once investor redemption requests accelerated across evergreen funds.
Industry-wide redemption gates, deferred withdrawals, and declining asset manager valuations indicate liquidity stress is no longer isolated, exposing fundamental weaknesses in semi-liquid private credit fund structures.
Investment exposure, refinancing risk, and banking interconnectedness are increasingly reinforcing one another, requiring boards and executives to evaluate enterprise-wide financial risks through a single integrated framework.
Corporate treasurers, CFOs, and boards should reassess liquidity assumptions, refinancing strategies, and consolidated risk reporting now, before tightening credit conditions reduce financial flexibility and funding availability.
Private credit’s first true stress test has exposed structural liquidity weaknesses across a $2 trillion asset class. With redemption pressure rising, regulators intensifying oversight, and risks spreading across funds, banks, and corporate borrowers, organizations that act early will be better positioned than those waiting for a broader market disruption.
Share On


 [email protected]
 +91 914 533 9262
 +91 (20) 46046669
 M 109 City Avenue, Shankar Kalat Nagar, Wakad, Pimpri-Chinchwad, Pune, Maharashtra, India - 411 057


Services
Sectors
Resources
Company